Watch Groups

hanuman chalisa in bengali pdf

Economy in Crisis -

Overview of Hanuman Chalisa in Bengali

The Bengali Hanuman Chalisa PDF presents the revered hymn in native script, offering devotees an accessible, faithful rendition. It preserves traditional verses while providing clear transliteration, making it ideal for study, recitation, and devotional practice across Bengal. Also, it supports screen readers.
Historical Roots and Popularity

The Hanuman Chalisa, composed by 16th‑century poet Goswami Tulsidas in Awadhi, has become a staple of Hindu devotion. In Bengal, early 20th‑century translators rendered the hymn into Bengali script, preserving its meter while adapting pronunciation. By the early 2000s, local scribes produced printed editions, and the first widely circulated Bengali PDF appeared in 2024, highlighted in a 2024‑07‑07 post that promoted a free “বলয় হনুমন চলস” download. This digital format increased accessibility, allowing devotees across urban and rural Bengal to read, recite, and share the Chalisa without physical copies.

Popularity surged during 2025–2026 when platforms like Bhakti Kosh and Ram Mandir Store released high‑resolution PDFs with full Bengali translations. The 2026‑01‑19 edition received praise for its “অত্যন্ত শুদ্ধ এব সহজবধ্য” rendering, described as authentic and user‑friendly. Community groups on social media circulated the PDF with transliteration guides, aiding non‑Bengali speakers. This digital ripple effect fostered a vibrant tradition that blends ancient devotion with modern technology, keeping the Hanuman Chalisa alive in Bengali spiritual life.

Additional releases—such as the 2025‑12‑14 free PDF on a devotional site and the 2025‑08‑10 post announcing a “FREE Download Hanuman Chalisa Bengali PDF”—attracted thousands of downloads, illustrating strong demand for accessible resources. The 2026‑01‑21 HinduNidhi offering, which included a Bengali transliteration, reinforced the trend of combining scriptural fidelity with user‑friendly presentation.

These cumulative efforts—spanning print, digital PDF, and community sharing—solidify the Hanuman Chalisa’s status as a ubiquitous devotional text in Bengal, honoring its historical roots while embracing modern distribution channels. Its legacy continues to inspire devotion generations!!!

The Bengali PDF editions of the Hanuman Chalisa blend textual fidelity with modern usability. Each file uses a clear, legible typeface that preserves the meter while ensuring readability. A side‑by‑side transliteration column is included, allowing non‑native speakers to trace pronunciation. The dual‑column layout aids memorization.

The PDFs also include a small glossary of key terms, helping new readers grasp the hymn’s symbolic references. Additionally, a built‑in search function allows quick navigation to specific verses, making the document useful for both study and daily devotion.

Many PDFs embed audio links that play verses in a traditional style. These cues sync with the text, letting users click a line to hear correct intonation. Some editions add color‑coded stanza separators, helping locate verses during recitations.

The color coding extends to the opening verses, where a subtle gradient marks the beginning, and to the concluding blessings, which are highlighted in a gentle hue. Users can toggle the color scheme on or off, ensuring a comfortable reading experience in low‑light conditions.

Accessibility is key. Documents are tagged with heading levels for screen readers. Text is selectable, letting users copy verses for study or paste into prayer journals. PDFs are mobile‑friendly, and versions are available in PDF/A and standard PDF formats.

The PDFs also feature a built‑in dictionary lookup, letting users tap a word for instant definition. The file size stays under 2 MB, enabling quick downloads.

The PDFs are also optimized for printing, with margins and line spacing that preserve the hymn’s rhythmic flow when printed on standard A4 paper.
Top Downloadable Sources

For those seeking the authentic Bengali rendition of the Hanuman Chalisa in PDF format, several reputable platforms provide reliable downloads. The most frequently cited sites are Bhakti Kosh, Ram Mandir Store, and HinduNidhi. Each offers a distinct version that caters to different preferences, whether you want a plain text layout, a richly illustrated edition, or a version that includes a side‑by‑side transliteration for easier learning. The files are typically lightweight, ranging from 1.5 MB to 2.5 MB, which ensures quick downloads even on slower connections. Users can also find community‑shared PDFs on social media groups dedicated to Bengali devotional literature, though these should be verified for authenticity before use. All major sources provide the direct download link, and some offer the option to view the PDF in a browser before saving it to your device. The download process is straightforward: click the link, confirm the file type, and the PDF will begin transferring. Once downloaded, the file can be opened with any standard PDF reader or shared with friends and family who appreciate the cultural heritage embedded in the hymn. It is advisable to keep a backup copy on a cloud drive or external storage to preserve the text for future use. By choosing a trusted source, you ensure that the hymn’s verses remain unaltered and that the accompanying transliteration is accurate, allowing you to recite with confidence and reverence. Download these PDFs responsibly, respecting copyright and sharing only with those who seek spirit growth cultural enrichment!
Step-by-Step Download Guide

Follow these simple steps to obtain the Bengali Hanuman Chalisa PDF from trusted sources. First, open your preferred web browser and navigate to the official Bhakti Kosh website. Once on the homepage, use the search bar to type “Hanuman Chalisa Bengali PDF” and press Enter. The search results will display a list of available downloads. Look for the entry that clearly labels itself as “Bengali” and verify the file size, which should be between 1.5 MB and 2;5 MB. Next, click the download button next to the correct entry. A pop‑up may appear asking you to confirm the download; click “Yes” or “Download” to proceed. The PDF will begin downloading automatically. If your browser prompts you to choose a location, select a folder that is easy to remember, such as “Documents” or “Downloads;” Once the download completes, locate the file in the chosen folder and double‑click it to open. The PDF viewer will display the hymn in Bengali script, along with a transliteration column. double‑click it to open. If you prefer to view the file online, right‑click the PDF link and select “Open in new tab.” In addition, some sites offer a “Print” button; clicking this will open a print preview dialog. From there, you can choose to print the PDF directly or save it as a new PDF file for offline use. Finally, for those who wish to share the PDF with friends or on social media, right‑click the file and choose “Share” or use the built‑in sharing options of your operating system. Always remember to respect copyright terms and avoid distributing the file to unauthorized parties. By following these steps, you can safely and efficiently obtain the Bengali Hanuman Chalisa PDF and incorporate it into your daily devotional routine.
Common Usage in Bengali Devotional Practices

In Bengal, the Hanuman Chalisa PDF is a cornerstone of daily worship, appearing on household altars, temple walls, and community screens. Families print the Bengali script version and place it beside the puja altar, where devotees recite verses aloud during morning puja, evening prayers, and special festivals such as Ram Navami and Hanuman Jayanti. The PDF’s clear, legible Bengali text allows both children and elders to read and chant the hymn, reinforcing linguistic heritage while invoking Hanuman’s protection. Many local temples distribute the PDF on USB sticks or CD‑ROMs, ensuring that even those without internet access can participate in devotional practice. In modern times, the Chalisa is shared via messaging apps; a short excerpt is sent to friends, and the PDF is uploaded to cloud storage for easy download. The hymn’s verses are frequently used as a meditation aid, with devotees pausing between lines to reflect on Hanuman’s virtues. Some families incorporate the PDF into “prayer cards,” placing a printed copy in a small box that is opened each morning. The rhythmic structure of the Chalisa makes it suitable for chanting groups, and the PDF’s layout often includes numbered stanzas to aid memorization. In addition, the Chalisa is used in schools, where teachers print the PDF for students to learn about Hindu mythology and Bengali literature. The accessibility features of the PDF—such as selectable text and zoom—allow visually impaired users to read the hymn with screen readers. Overall, the Hanuman Chalisa PDF serves as a versatile tool that bridges tradition and technology, ensuring that the devotional practice remains vibrant across generations. This PDF is available for download, sharing, study, ensuring that every devotee can connect with Hanuman’s grace..
Cultural Significance in Bengal

In Bengal, the Hanuman Chalisa PDF is a living testament to the region’s devotional heritage, intertwining faith, literature, and community identity. The Bengali rendition, rendered in native script, preserves the rhythmic meter of the original while offering a familiar linguistic experience for Bengali‑speaking devotees. It is widely used in household altars, temple shrines, and community gatherings, where families print the PDF and place it beside the puja altar, allowing children and elders alike to recite the hymn aloud. The PDF’s clear, legible Bengali text also makes it a staple in schools, where teachers incorporate it into Bengali literature curricula, linking religious tradition with academic study. During festivals such as Ram Navami, the Chalisa is projected on large screens in public spaces, inviting crowds to chant in unison, fostering a sense of collective identity. The accessibility of the PDF has enabled diaspora communities to maintain ties with their homeland, as families print the text and share it in virtual prayer circles. Moreover, the Chalisa’s themes of devotion, courage, and divine protection resonate with Bengal’s historical narratives of resilience, echoing the spirit of the Bengal Renaissance and the region’s struggle for independence. The digital availability of the PDF has spurred contemporary artists to create graphic adaptations, blending traditional calligraphy with modern design, further embedding the hymn into Bengal’s visual culture. In academic circles, researchers cite the PDF as a primary source for studying the evolution of Bengali devotional literature, noting its role in preserving oral traditions in written form. Thus, the Hanuman Chalisa PDF stands as a living testament to Bengal’s enduring spiritual heritage, bridging past and present through accessible, culturally resonant scripture.
Legal and Ethical Considerations for PDF Distribution

Distributing Hanuman Chalisa PDFs must respect copyright laws. Use only authorized versions or public‑domain texts. Ensure proper attribution, avoid commercial use without permission, and comply with local regulations. Ethical sharing promotes respect for sacred content. Verify authenticity before sharing Help

Bhakti Kosh and Ram Mandir Store Offerings
Bhakti Kosh and Ram Mandir Store are two prominent online platforms that provide high‑quality Bengali versions of the Hanuman Chalisa in PDF format. Both sites emphasize authenticity, offering texts that are carefully transcribed from traditional manuscripts and verified by scholars familiar with regional linguistic nuances. Users can download the PDF for free or purchase a premium edition that includes additional features such as annotated verses, audio recitations, and high‑resolution images of the original calligraphy. The PDFs are available in multiple file sizes, ensuring compatibility with a range of devices from smartphones to desktop computers. Both platforms maintain strict copyright compliance, providing clear licensing information and ensuring that the distribution of the Chalisa respects the rights of the original authors and publishers. For those seeking a deeper devotional experience, the sites also offer companion resources such as guided meditation scripts, prayer schedules, and community forums where devotees can share insights and personal reflections. The user interface is designed to be intuitive, with search functions that allow quick navigation to specific verses or themes. Accessibility is a priority; the PDFs are formatted with selectable text, enabling screen readers to interpret the content for visually impaired users. In addition, both Bhakti Kosh and Ram Mandir Store provide multilingual support, allowing non‑Bengali speakers to access transliterations and translations in Hindi, English, and other regional languages. The platforms regularly update their libraries to include newly published editions and to correct any typographical errors identified by the community. By fostering a digital repository that respects both tradition and modern technology, these platforms ensure that the spiritual legacy of the Hanuman Chalisa remains accessible to future generations. Users can also contribute feedback, helping the sites refine the PDFs and incorporate user‑requested enhancements such as color‑coded verses for easier study. The commitment to quality control means that every download undergoes a final review for typographical accuracy, layout consistency, and compliance with religious guidelines. Consequently, devotees can trust that the PDFs they receive are not only legally sound but also spiritually authentic, allowing them to engage fully with the text in their daily worship and communal gatherings. Moreover, the platforms provide a subscription model that grants members early access to limited‑edition prints and exclusive audio sessions featuring renowned reciters. This model supports the ongoing maintenance of the digital archives and encourages sustained engagement among the faithful.
Free PDF Offerings Through HinduNidhi

HinduNidhi has emerged as a reliable source for devotees seeking a freely downloadable Bengali rendition of the Hanuman Chalisa. The platform hosts a dedicated section where users can access a PDF that faithfully reproduces the original verses in the Bengali script, complete with accurate transliteration and concise English translations for broader comprehension. The PDF is available at no cost, ensuring that anyone with an internet connection can obtain the text for personal study or devotional use. HinduNidhi’s interface is user‑friendly, featuring a straightforward download button and a brief description that outlines the file’s contents, including the number of verses, the presence of a commentary, and the file size. The site also provides a brief background on the text’s origin, noting that the Bengali version is adapted from the traditional Sanskrit Chalisa while preserving the devotional tone and rhythmic cadence that devotees cherish. In addition to the PDF, HinduNidhi offers supplementary resources such as audio recitations in Bengali, allowing users to listen to the verses while following along with the printed text. This multimodal approach caters to different learning styles and enhances the spiritual experience. The platform’s commitment to accessibility is evident in its adherence to web standards, ensuring that the PDF can be opened on a range of devices, from smartphones to desktop computers. Users can also share the PDF on social media or within community groups, fostering a sense of collective worship. HinduNidhi’s policy is transparent about copyright; the PDF is distributed under a license that permits personal use but restricts commercial exploitation, thereby respecting the intellectual property rights of the original authors and translators. The site encourages feedback, inviting readers to report any typographical errors or formatting issues, which are promptly addressed by the support team. This iterative process helps maintain the quality and reliability of the resource over time. For those interested in a deeper study, HinduNidhi occasionally releases annotated versions that include footnotes explaining cultural references, mythological context, and linguistic nuances. These editions are also free, reinforcing the platform’s mission to democratize access to sacred texts. Overall, HinduNidhi’s free PDF offerings provide a convenient, trustworthy, and legally compliant means for Bengali‑speaking devotees to engage with the Hanuman Chalisa, supporting both individual devotion and communal worship practices.

Transliteration Accuracy and Script Variants

The Bengali Hanuman Chalisa PDF presents the hymn in native Bangla script with a Latin‑based transliteration following IAST guidelines. This dual‑script format allows non‑Bangla readers to trace phonetics while appreciating original orthography. Accuracy is maintained by cross‑checking against the Devanagari source, ensuring consonant clusters, vowel diacritics, and conjunct forms are correct. For instance, Bangla “শ” is transliterated as “ś”, and “ন” as “n”. A brief key maps Bangla characters to Latin equivalents, aiding scholars and practitioners comparing regional versions.
Script variants are evident in how diacritics are handled. The Bangla “ং” (anusvara) is transliterated as “ṃ”, while “ঃ” (visarga) becomes “ḥ”. Some publishers offer a Devanagari overlay, letting users toggle between Bangla and Devanagari scripts within the same PDF. This feature uses annotations that preserve the Bangla text while overlaying the Devanagari equivalent, enabling side‑by‑side comparison. The transliteration section is formatted in a monospaced font to maintain alignment, and line numbers aid reference during group chanting.

Some PDFs also include an IPA guide that annotates each verse with phonetic symbols, offering a granular representation of pronunciation nuances such as breathy voice or retroflex consonants. This optional appendix is typically found at the end of the document, making the text useful for advanced linguistic study.

It supports both devotion and study.

Accessibility Features in PDF Format

The Bengali Hanuman Chalisa PDF incorporates several accessibility features to support diverse users. First, the document is tagged with semantic structure, allowing screen readers to navigate headings, paragraphs, and lists in logical order. The Bangla text is encoded in Unicode, ensuring correct rendering on all devices.

For visually impaired readers, the PDF offers an optional high‑contrast mode and a zoom‑in capability that preserves line integrity. The file includes an embedded text layer, enabling copy‑paste and search functions across the entire hymn. Additionally, a separate “alt‑text” description accompanies each stanza, summarizing the meaning in plain English.

  • Tagged structure with h1, h2, p, and li elements.
  • Unicode Bangla characters and Latin transliteration.
  • High‑contrast and scalable fonts.
  • Embedded text layer for searchability.
  • Alt‑text summaries for screen readers.

These features comply with WCAG 2.1 Level AA guidelines, ensuring that the devotional content is accessible to users with visual, auditory, or motor impairments. The PDF also supports navigation bookmarks that link directly to each verse, facilitating quick access during recitation or study sessions.

Accessibility tools such as adjustable font size, contrast toggles, and screen‑reader navigation enable a broad audience to engage with the text. Users can also export the PDF to audio formats for listening.

Community Sharing Practices on Social Media

In the digital age, devotees frequently circulate the Bengali Hanuman Chalisa PDF through popular platforms such as WhatsApp, Facebook, Instagram, and Telegram. Users often attach a short devotional caption, include the hashtag #HanumanChalisaBengali, and link to a trusted source like Bhakti Kosh or HinduNidhi.

WhatsApp groups, in particular, serve as informal libraries; members forward the PDF as a single file, ensuring that the original formatting and embedded tags remain intact. On Facebook, users post the PDF as a downloadable attachment, sometimes embedding a preview image of the first page to entice viewers.

Telegram channels provide a more structured approach: administrators post the PDF with a pinned message, and subscribers can download it directly. These channels also offer a discussion forum where followers can ask questions about the verses’ meanings or request a printable version.

To maintain respect for the text, many sharers include a brief disclaimer that the PDF is for personal devotional use only and encourage recipients to verify the source.

Overall, the community sharing ecosystem around the Bengali Hanuman Chalisa PDF is vibrant, mindful of accessibility and ethical considerations, ensuring that the hymn remains widely available while preserving its sanctity. This underscores that transcends regional boundaries, fostering unity followers across the worldwide.

Preservation Efforts for Bengali Religious Texts

Preserving the Bengali Hanuman Chalisa PDF involves a multi‑layered strategy that blends technology, community engagement, and archival science. Digital libraries such as the Digital Library of Bengal and the National Mission for Manuscripts digitize original manuscripts, converting delicate calligraphic pages into high‑resolution PDFs that retain every diacritic and marginal note. These PDFs are then hosted on open‑access platforms like Bhakti Kosh and HinduNidhi, where they can be downloaded, printed, or shared on social media without compromising the text’s integrity.

Academic collaborations further strengthen preservation. The University of Calcutta’s Department of Indology partners with software developers to create OCR tools specifically tuned to Bengali script. These tools correct common scanning errors, preserve ligatures, and embed metadata that makes the PDFs searchable and cross‑referencable with other devotional works. The resulting files are stored in PDF/A format for long‑term preservation and PDF/UA for accessibility, ensuring compliance with international archival standards.

Community‑driven initiatives, such as the “Bengali Scriptures Digitization Drive,” mobilize volunteers to transcribe handwritten verses, verify transliterations, and annotate contextual footnotes. A peer‑review model maintains scholarly rigor while fostering a sense of ownership among local devotees. Annotated PDFs are uploaded to open‑access repositories, where they can be downloaded, printed, or shared on social media, further extending their reach.

To guard against data loss, redundant backups are kept on cloud services and climate‑controlled physical media; Regular integrity checks detect corruption, and PDFs are periodically re‑encoded to newer standards to prevent obsolescence. This layered approach—combining digitization, community participation, and rigorous archival practices—ensures that the Bengali Hanuman Chalisa remains a living, accessible text for all who seek its blessings.

The post hanuman chalisa in bengali pdf appeared first on Every Task, Every Guide: The Instruction Portal
.

IMCO Restructures its Leadership, CIO to Depart in New Year

Pension Pulse -

Lauren Bailey of Markets Group reports IMCO is restructuring its investment leadership as CIO readies to depart:

The Investment Management Corp. of Ontario (IMCO) is moving away from a single chief investment officer model as Rossitsa Stoyanova prepares to leave the role in January 2027.

IMCO plans to distribute her responsibilities among three senior investment executives, according to a press release. Rather than appoint a direct successor, the fund will divide responsibilities previously held by the CIO across its total portfolio, private markets and public equities functions.

Nick Chamie, currently senior managing director of total portfolio and capital markets and chief strategist, will become executive managing director of total portfolio. Craig Ferguson, senior managing director and head of private equity and global credit, will become executive managing director of private markets, while Angus Botterell, senior managing director and head of public equities, will become executive managing director of public equities.

All three will report directly to President and Chief Executive Officer Bert Clark and join IMCO’s senior executive team.

Stoyanova, who has served as CIO since September 2021, will remain in the role through January to oversee the transition before becoming a special advisor to IMCO. The organization said she has decided to pursue her “next professional chapter.”

In the release, Clark said Stoyanova has played a pivotal role in strengthening IMCO’s investment platform and helping shape the organization. “We are grateful for her many contributions and pleased that she will continue to support the organization during this important transition,” he said.

Stoyanova joined IMCO from CPP Investments, where she held several senior roles across the total portfolio, including managing director and head of portfolio design and construction, with responsibility for portfolio design, risk appetite and allocation. Before joining CPP Investments, she worked at GE Energy Financial Services and Deloitte & Touche.

During her tenure, IMCO continued to build out a more integrated investment platform combining asset-class investing with total portfolio asset mix, liquidity and risk management. The organization also expanded its internal investment capabilities and strategic partnerships across public and private markets.

IMCO said the new leadership structure reflects the growing scale and complexity of its investment platform and is intended to create greater focus across key investment disciplines while promoting senior talent from within.

“These appointments are a natural progression of our strategy,” Clark said. “We have deliberately built a strong investment team, and promoting outstanding leaders from within strengthens our culture, deepens collaboration and increases organizational resilience.”

IMCO manages C$90.7 billion on behalf of Ontario public-sector clients and provides investment management services, including portfolio construction, access to public and private asset classes and risk management. 

Benefits Canada also reports IMCO restructuring investment leadership following CIO’s departure: 

Rossitsa Stoyanova is leaving the Investment Management Corp. of Ontario as chief investment officer, effective January 2027.

She will become a special advisor to the investment organization after transitioning from the CIO role. In response, the IMCO will evolve the CIO role to a broader investment leadership function and make several leadership structure changes.

Nick Chamie will become executive managing director of total portfolio, while Craig Ferguson will become executive managing director of private markets and Angus Botterell will be named executive managing director of public equities. All three will join the senior executive team at the investment organization and report directly to president and chief executive officer Bert Clark.

The leadership changes reflect the growing scale and complexity of the IMCO’s investment platform, according to a press release.

“Rossitsa has played a pivotal role in strengthening our investment platform and helping shape the organization we are today,” Clark said in the release. “We are grateful for her many contributions and pleased that she will continue to support the organization during this important transition.”

IMCO announced the investment leadership appointments back in August:

  • Expanded leadership structure reinforces continuity, deepens investment expertise and positions IMCO to deliver long-term value for clients

TORONTO (August 7, 2026) – The Investment Management Corporation of Ontario (“IMCO”) today announced changes to its investment leadership team following Chief Investment Officer Rossitsa Stoyanova's decision to pursue her next professional chapter.

Stoyanova will remain Chief Investment Officer through January 2027 to ensure a seamless transition before becoming Special Advisor to IMCO.

IMCO will use the transition to evolve the Chief Investment Officer role into a broader investment leadership function. Accountabilities that previously sat with one executive will be distributed across senior leaders with complementary expertise, strengthening execution across IMCO’s multi-client platform and creating growth opportunities for proven internal talent.

"Rossitsa has played a pivotal role in strengthening our investment platform and helping shape the organization we are today,” said Bert Clark, President and Chief Executive Officer. “We are grateful for her many contributions and pleased that she will continue to support the organization during this important transition."

Effective January 2027:

  • Nick Chamie, currently Senior Managing Director, Total Portfolio and Capital Markets and Chief Strategist will become Executive Managing Director, Total Portfolio.
  • Craig Ferguson, currently Senior Managing Director, Head of Private Equity and Global Credit will become Executive Managing Director, Private Markets.
  • Angus Botterell, currently Senior Managing Director, Head of Public Equities will become Executive Managing Director, Public Equities.

Each will report directly to the President and CEO and join IMCO's Senior Executive Team.

The new structure reflects the growing scale and complexity of IMCO’s investment platform, creates greater focus across key disciplines and reinforces IMCO’s commitment to developing exceptional leaders from within.

“These appointments are a natural progression of our strategy,” said Clark. “We have deliberately built a strong investment team, and promoting outstanding leaders from within strengthens our culture, deepens collaboration and increases organizational resilience. Most importantly, it positions us to deliver even stronger long-term outcomes for our clients.”

The appointments build on IMCO’s differentiated investment philosophy, which emphasizes broad diversification, disciplined risk and liquidity management, cost-effective implementation and a long-term investment horizon. Managing client portfolios holistically helps strengthen portfolio resilience and efficiency while positioning clients to capture long-term opportunities.

"Our strategy has never depended on any one individual," added Clark. "It depends on building enduring institutional capability. The depth of talent we have developed gives us tremendous confidence in the future and ensures continuity for our clients as we continue to grow."

About IMCO

The Investment Management Corporation of Ontario (“IMCO”) manages $90.7 billion of assets on behalf of its clients. Designed exclusively to drive better investment outcomes for Ontario's broader public sector, IMCO operates under an independent, not-for-profit, cost recovery structure. We provide leading investment management services, including portfolio construction advice, better access to a diverse range of asset classes and sophisticated risk management capabilities. As one of Canada's largest institutional investors, we invest around the world and execute large transactions efficiently. Our scale gives clients access to a well-diversified global portfolio, including sought-after private and alternative asset classes. Follow us on LinkedIn and X @imcoinvest. 

Alright, someone emailed me inconspicuously this morning to let me know about the leadership restructuring that took place at IMCO.

My apologies; this story came out in early August, and I totally missed it.  

I must admit, I don't track IMCO closely, but I should have lumped this with my discussion on senior departures at HOOPP and CPP Investments a month ago.

Also, to be brutally honest, my attention these days is almost exclusively on markets, a lot less on pensions.

So, my bad for not covering events at IMCO last month; let me share my thoughts quickly.

First, I am sad to see Rossitsa leave the role of CIO at IMCO. I thought she was doing an excellent job there over the last five years (she was appointed CIO of IMCO in August 2021, replacing Jean Michel).

IMCO's press release states she will be staying on till January after which she will shift into the role of  "special advisor" as she prepares for her next "professional challenge".

Between you and me, that's a polite way of showing someone the door, you pay them off, ask them to remain in the role till the new year begins and "transition them to the role of special advisor".

Again, I might be wrong, maybe she has another job lined up like Lori Hall-Kimm who joined her former boss at CPP Investments, Alain Carrière, over at Abu Dhabi Investment Council, but it is odd that Rossitsa isn't staying on as CIO at IMCO.

Now, to be fair to Bert Clark, maybe he tried the CIO approach for five years and wants to try something different. There is nothing edged in stone that a large pension fund has to have a CIO.

La Caisse doesn't have one (only a head of Liquid Markets). BCI's CEO, Gordon Fyfe, also assumes the role of CIO, a hat he seems reluctant to part with ever since I knew him in 2002 at La Caisse and then subsequently in 2003 at PSP.

OMERS recently restructured its leadership after its CIO, Ralph Berg left the organization and CEO Blake Hutcheson gave more responsibility to Michael Hill and other senior executives who will report directly to him.

OTPP has two co-CIOs who are in charge of total portfolio and liquid and private markets and it seems to be working well for them. 

But there's nothing set in stone that a large pension fund has to have a CIO.

In fact, some people hate it, others love it. All I can tell you is if you don't put the right, competent person as a CIO and give them ample power across public and private markets, then it can backfire on the organization.

CIOs like Bob Bertram and the late Neil Petroff are my benchmark for outstanding CIOs, and they don't come around often.

All this to say, maybe there were legitimate reasons for Bert Clark to promote his boys -- Nick Chamie, Craig Ferguson, and Angus Botterell -- and get rid of Rossitsa and the position of CIO, but let me tell you, if I was a client of IMCO, I'd be ripping into Bert Clark and the Board, asking a lot of pertinent questions. 

Notice I said to promote his "boys"? I find it strange that the two most senior female investment executives at IMCO recently left the organization.

Back in May, Jennifer Hartviksen, IMCO's former global head of Credit, announced on LinkedIn she left the organization to head up Fixed Income at TD Asset Management.

So, two women, big positions at IMCO, replaced by men.

"So what Leo, who cares, let the men reign for once, everything is DEI hires these days."

Trust me, I don't have an issue with promoting competent men (key word is competent), but the optics don't look good, especially to IMCO's clients, many of which are women.

The other thing I'm going to throw out there to all pension fund leaders is that immigrants are taking over Canada. They might have funny names with lots of vowels, but they are increasingly moving up the socioeconomic ranks and if they're not properly represented at all levels of your organization, well, shame on you!!

It's about time that immigrants or sons and daughters of immigrants get their fair share of representation at all our large pension funds and here I will not mince my words: some organizations are doing a much better job than others at hiring a diverse workforce across all levels, including senior levels.

"Well Leo, we cannot have people with funny sounding names at senior levels of a large Canadian pension fund, doesn't look, well, Canadian."

Bullocks!! Absolute rubbish!! Put the best person in charge regardless of their name, religion, gender, sexual orientation, color of their skin, or disability (don't get me started on that last one).

So yeah, maybe Bert Clark had legitimate reasons to restructure his leadership and get rid of the CIO position, but the optics of all this do not look particularly good for IMCO and could send the wrong message to women and Canadian allophones busting their ass to get into these shops. 

"Leo, come on, nobody really cares; it's all part of the game. Politics looms large at these large shops. In a year, nobody will remember Rossitsa Stoyanova or Jennifer Hartviksen ever worked at IMCO, just like people forgot all about Jean Michel."

Maybe, but here is my warning to Bert Clark and IMCO's Board: be very careful about how you are perceived out there, or you risk attracting B-types at your organization (I'm dead serious). 

Alright, back to markets and trading. Unlike the pension aristocracy I cover here, I have to eat what I kill.

I wish Rossitsa Stoyanova all the best in her next professional challenge; it was a pleasure conversing with her a couple of times while covering IMCO properly. 

Below, the CNBC Investment Committee debates how they're setting up their portfolios as we head into the fourth quarter.

Also, Glen Smith, chief investment officer at GDS Wealth Management, joins BNN Bloomberg to discuss the impact of bonds and inflation on the markets. 

Rising rates are already hitting the US housing market and that's not good if unemployment rises significantly. 

BCI's 2025-2026 Stewardship Report

Pension Pulse -

Today, BCI released its 2025-2026 Stewardship Report: 

British Columbia Investment Management Corporation (BCI), one of Canada’s largest institutional investors, today released its 2025-2026 Stewardship Report, demonstrating continued environmental, social, and governance (ESG) leadership and measurable progress through engagement, proxy voting, and policy dialogue. 

“In a year that tested active owners, BCI advanced our stewardship program with the same conviction and persistence we have held for more than 20 years,” said Jennifer Coulson, BCI’s Senior Managing Director & Global Head, ESG. “Consistency is an advantage, and our approach is driving improvements in our portfolio and creating long-term sustainable value for our clients.” 

Last year, BCI directly engaged 181 public and private portfolio companies on material ESG risks and opportunities, reaching thousands more through collaborative initiatives. Of the in-depth engagements, 44% showed positive momentum and 8% achieved objectives outright, illustrating that constructive dialogue can deliver real-world outcomes.  

Notable multi-year engagement successes include contributions towards Scotiabank becoming the first Canadian bank to publicly disclose its Energy Supply Financing Ratio; Samsung Electronics incorporating climate metrics into executive compensation and setting a new 2030 emissions target; and Valence Surface Technologies investing US$5.7 million in environmental, health, and safety enhancements.  

“As the investment landscape grows more complex and interconnected, we continue to see good governance as the foundation everything else relies on,” added Coulson. “The willingness of boards and management to engage signals alignment on long-term performance and a commitment to managing material risks and opportunities.”  

BCI continued to cast ballots for public companies across its portfolio during the 2026 proxy season, a total of 2,209 meetings across 55 countries. This included voting against 26% of management proposals based on a careful assessment of governance practices and oversight of environmental and social risks. New analysis of BCI’s proxy voting record found that companies receiving BCI’s lowest levels of support for management proposals were also 1.6x more likely to see sharp declines in share price than companies receiving the highest support over a five-year period. While not predictive, understanding the potential relationship between voting practices and financial performance reinforces the importance of using shareholder rights to hold management and boards accountable. 

BCI Stewardship highlights 2025-2026 
  • Building climate resilience: Expanded engagement on physical climate risk across the infrastructure portfolio, working closely with private holdings like Endeavour Energy and Cube Highways, as extreme weather events increasingly factor into long-term asset performance. 
  • Evolving methane measurement: Convened companies across the Canadian LNG value chain on methane measurement as a credibility signal and commercial differentiator. Following engagement, TC Energy tied executive pay to a new 2035 methane reduction target and Tourmaline Oil became the first company to certify an integrated gas production and processing system under MiQ, a global methane certification standard.  
  • Generating value in private markets: Worked with 19 private portfolio companies and 26 general partners to strengthen and support sustainability initiatives. BCI hosted its second ESG Value Creation Conference in New York and collaborated with Stanford University’s Long-Term Investing Initiative on original research linking ESG practices to financial performance. 
  • Strengthening responsible AI expectations: Tailored approach to AI engagement to distinguish between developers, deployers, and the broader value chain, joined the World Benchmarking Alliance’s Collective Impact Coalition for Ethical AI, and continued comprehensive dialogue with Amazon on AI governance and infrastructure impacts. 
  • Advancing Indigenous relations: Engaged Canadian firms on implementing their reconciliation commitments, including Agnico Eagle Mines, Enbridge, Hydro One, and Hydro-Québec. BCI reinforced foundational expectations with management, while supporting corporate certification and equity participation initiatives. 

Read the 2025-2026 Stewardship Report. 

This stewardship reporting is complementary to the ESG and climate-related disclosures available in BCI’s 2025-2026 Corporate Annual Report.  

I don't normally cover every stewardship report our pension funds put out except for those of La Caisse and BCI because they are widely recognized as leaders in the field.

Take the time to read BCI's 2025-26 Stewardship report here. 

At a minimum, read what BCI's Head of ESG, Jennifer Coulson has to share: 

The part about consistency is their advantage is spot on, as is proper communication with private and public companies as to what their expectations are.

The other thing worth noting is how once again,BCI notes extreme weather now factors into their infrastructure investments.

Last year, Jennifer Coulson shared this with Jeffery Jones of The Globe and Mail:

Investors are taking different approaches to the issue. Jennifer Coulson, senior managing director and global head, ESG, for British Columbia Investment Management Corp. (BCI), said physical risk assessment affects both macro and micro calculus.

“We have to be aware of the broad trends and what’s happening, and so physical climate-change risk is captured in the climate change scenario work that we do at the total portfolio level,” Ms. Coulson said.

“But then you really have to understand the implications of that from a bottoms-up perspective as well. As we are making investment decisions, we need to make sure that this is factored into, particularly, some of the hard assets that we would be holding for, in some cases, decades.”

Acquiring the right data, and tools for slicing and dicing it, is a top challenge as BCI looks to prepare for a range of scenarios, she said.

In its recently released Stewardship Report, BCI listed physical and transition risks as its first priority in engagements with portfolio companies, saying they threaten asset value, can increase operational costs and disrupt supply chains. 

Anyway, take the time to read BCI's latest Stewardship report here.

Below, earlier this summer, Jennifer Coulson took part in a panel discussion at Finance Montreal moderated by Hervé Duteil, Head of ESG at BNP Paribas Americas. Have a listen; excellent insights.

Canada's Large Pension Funds Want Stakes in Our Airports

Pension Pulse -

Andrew Willis of The Globe and Mail reports Canadian airports can anchor a global infrastructure champion:

If you are reading this while killing time waiting for a flight in one of Canada’s major airports, you are sitting in what should be the country’s next global corporate champion.

The federal government’s long-overdue decision to sell concessions in four major domestic hubs – Vancouver, Calgary, Toronto and Montreal – promises to be a win for passengers and taxpayers. After years of analysis paralysis, Prime Minister Mark Carney has an opportunity to improve the passenger experience while raising billions of dollars.

The ultimate goal in this exercise, clearly visible to a Prime Minister who started his career as a Goldman Sachs banker advising governments on privatizations, should be creating a private-sector operator of Canadian airports that does business around the world.

At least one domestic pension fund, Montreal-based PSP Investments, is already well down this runway.

In June, months before Mr. Carney announced plans to sell airport concessions at last Tuesday’s Canada Investment Summit, Montreal-based consultant Fethi Chebil published a sector study that started with a metaphysical question for the government.

“What is an airport for? An asset to sell, or a tool to build a national operator?” Dr. Chebil said in his June report.

For governments, Dr. Chebil concluded that launching a business beats selling a few terminals. To support his argument, Dr. Chebil pointed to the success that Canada’s largest pension funds have enjoyed internationally as owners of airport operators, and the virtues of this model for frequent flyers.

The poster child for airport operators globally is PSP, which pays for the retirements of soldiers, Mounties and civil servants. The $321-billion fund manager has built a global business that should serve as a road map for Canadian airport ownership.

In 2013, PSP acquired a collection of European airports from a German infrastructure fund for €1.1-billion. The wholly owned subsidiary, branded as AviAlliance, now operates seven facilities in Scotland, Germany, England and Puerto Rico.

AviAlliance is the largest holding in a PSP infrastructure portfolio that handily beat performance benchmarks over the past decade.

AviAlliance airports also charge travellers less for food, beverages and fees than Canadian airports, according to Dr. Chebil’s research. Domestic airports operate as non-profit, debt-funded Crown corporations, a cumbersome, only-in-Canada ownership approach devised in 1992. Dr. Chebil said in his report: “The 1992 structure is not delivering lower costs to users.”

Private airport owners would create more opportunities for travellers to drop stupid amounts of money on cucumber-lined Hendrick’s martinis or Rolex watches. That’s discretionary consumer spending. Want to curtail the cost of a trip? Avoid airport restaurants and retailers.

The experience in Europe and Australia, where governments sold airport concessions, is to keep costs down by regulating fees on monopoly services such as baggage handling or aeronautical services including navigation. Governments use the same approach to ensure pipeline operators and electrical utilities don’t gouge consumers.

In 2016, former federal finance minister Bill Morneau launched an economic review that said selling airports was among the best options for a government that needed to find money for infrastructure projects. A decade later, Mr. Carney is following through.

For insight into how the Prime Minister thinks about finance, recall Mr. Carney’s pointed criticism of the billions in “dead money” on corporate balance sheets back in 2012, when he was governor of the Bank of Canada.

In a Q&A after a speech to the Canadian Auto Workers union, the then-central banker took CEOs and boards to task for being excessively cautious by sitting on cash, rather than investing in growth or returning money to shareholders.

There is a straight line from what Governor Carney said about dead money years ago to what Prime Minister Carney announced on airports last week.

Last Tuesday, in his opening speech at the investment summit, Mr. Carney said by selling airport concessions, while retaining ownership of the assets, “we will unlock their true value, by bringing in new capital and expertise into their operations and growth.”

“We will reinvest the tens of billions of dollars of capital we raise into the infrastructure that Canada needs,” the Prime Minister said.

Airports represent dead money on the federal government’s balance sheet. Selling concessions to operate Vancouver, Calgary, Toronto and Montreal’s terminals can make flying more pleasant, without boosting the cost of travel.

And placing the country’s four major airports in the proven hands of a fund manager such as PSP could create a global champion in a critical infrastructure sector. 

I wanted to kick this week off by discussing Canadian airports again.

Andrew Willis, citing Dr. Fethi Chebil, goes over many important points as to why we want to privatize airports.

In short, private airport owners would create more opportunities for travellers to enjoy the airport experience by enhancing the operations through a myriad of ways.

One thing I want to correct Andrew Willis on: airports aren't dead money for the federal government; they are a cash cow, which explains the reticence to privatize them.

But enough is enough. Canadian travellers deserve a better experience and better airport operators who understand these assets and know how to manage them properly.

If our pension funds -- not just PSP but OTPP and others including international funds -- can add value to our airports, and make money in the process, I am more than fine with that. 

The sooner we get on with it, the better. Let the unions complain; it's high time we join the rest of the world and make our airports world-class (they are far from it).  

Anyway, let's get on with it already and carve out these airports to the biggest and best funds domestically and internationally. 

Below, Jo Taylor, CEO of the Ontario Teachers' Pension Plan, joins BNN Bloomberg's Lindsay Biscaia live from the Canada Investment Summit. Listen carefully to what he says when asked about enhancing value at our airports (around minute 3:40). 

Also, a corporate video on AviAlliance, PSP's airport platform, one of the most successful in the world.

Meta's Muse Propels Mag-7 Higher Despite Rising Yields

Pension Pulse -

Sean Conlon, Justina Lee and Tobias Burns of CNBC report the Dow jumps more than 470 points Friday; stocks notch winning week despite Treasury yield surge:

U.S. equities rose on Friday as Wall Street wrapped up a volatile week of trading, with a surge in Treasury yields rippling through financial markets.

The S&P 500 climbed 0.51% to close at 7,743.41, while the Nasdaq Composit gained 0.5% to 27,068.72. The Dow Jones Industrial Average advanced 478.64 points, or 0.93% to end at 51,828.62.

Akamai Technologies was a key winner of the session, rising 3% after announcing a multiyear deal with Anthropic.

Also helping sentiment, oil prices slid amid optimism that the Strait of Hormuz could be reopened, as Iran has asked the U.S. to return to the memorandum of understanding from June that failed to end the Middle East conflict. West Texas Intermediate crude futures dropped 2.33% to settle at $92.41 per barrel, while international benchmark Brent crude futures declined 2.14% to $104.32 a barrel.

With the day’s gains, the Dow notched a winning week, up 0.3%. The S&P 500 added 1.2%, while the Nasdaq rose 2%.

That advance was bolstered by technology stocks such as Meta Platforms, which popped nearly 13% on the week amid excitement surrounding its artificial intelligence agent Muse. Information technology rose 3.1%, which was the most of any of the S&P 500′s sectors.

The drama continued in the bond market, where the 10-year Treasury yield climbed to its highest level since 2007, while the 30-year yield reached its highest level since 2004. The two were last seen up slightly at 5.163% and 5.488%, respectively.

This week’s ascent in yields was fueled by hawkish comments from Federal Reserve Governor Michael Barr, persistently high energy prices due to the Iran war, and a hot purchasing managers’ report. Fed funds futures trading suggests a roughly 64% likelihood of a rate hike in October, according to the CME FedWatch tool.

Eric Diton, president of The Wealth Alliance, noted that investor sentiment has been weakening as bond yields have been rising, with bearish sentiment seeing a “sharp” increase from just two weeks earlier. That said, he believes the market has been “incredibly resilient” in the face of the developments, with the S&P 500 and Nasdaq roughly 1% below their recent highs.

“Should rates continue to climb, they should have a larger impact on market performance at some point in the future,” he cautioned.

Meanwhile, traders were monitoring Chinese President Xi Jinping’s visit to the U.S. this week. U.S. Trade Representative Jamieson Greer told CNBC Friday that “a lot more details” on negotiations between the U.S. and China are going to be released Monday.

Treasury Secretary Scott Bessent said earlier in the week that the two countries have agreed to extend their trade truce by two months. 

The big story this week was shares of Meta Platforms (META) surging to a new 52-week high as the company released its new Muse Charm device, which is intended to put it ahead of rivals like OpenAI and Google in AI agents and consumer hardware (read more here):


Look at the weekly 5-year chart above, the never broke below its 200-week exponential moving average. It was a buy near $500 (its 52-week low was $520 a share). And this week it made a new 52-week high before giving up some gains today (the stock is up 32% over the past month).

I didn't need to listen to the talking heads on CNBC to figure out that it was only a matter of time before this stock turns up. At the end of the day, Meta is a cash cow just off Instagram and it seems like all that spending on AI is finally paying off (but they need to demonstrate they're gaining a foothold in the corporate market).

What else? Shares of Microsoft (MSFT) are up nicely today after CEO Satya Nadella said its cloud-based Autopilot is the 'next generation' of enterprise AI (see his comments here).


Microsoft's share price bounced nicely off its 52-week low of $349 and the stock remains in a bullish uptrend despite the lackluster performance over the past month.

More generally, the Roundhill Magnificent Seven ETF (MAGS), which tracks the performance of the “Magnificent Seven,”is back firmly in bullish mode, breaking out and making a new 52-week high:


Also worth noting the iShares MSCI USA Momentum Factor ETF (MTUM), which holds all the top memory chip makers, is turning back up and looking great again:

 Conversely, the Invesco S&P 500 Equal Weight ETF (RSP), which is a broader measure of the market, is turning back down and selling off here as we close the quarter (FOMO kicking in hard):

This is what we have seen all year: either Mag-7 stocks are doing well or the broader market is doing well but rarely, if ever, both are rallying.

Capiche? this is what you need to pay attention to, never mind bond yields back at 2007 levels and all the scary stories about that.

Can the 10-year US Treasury yield touch 6% this year? Sure it can, and I guarantee you every pension fund in the world will be jumping on them at that point, but I doubt yields will back up a lot more here (because already global allocators are buying bonds and unless you have nasty inflation surprises, not going to happen).

In fact, just looking at the iShares 20+ Year Treasury Bond ETF (TLT), which is a price index, I can tell you bonds are starting to look mighty attractive at these levels (but prices can fall further):

There is a point where global pension funds say, "screw this", we are not being compensated enough to take risks in stocks, hedge funds, private equity, private credit, real estate, infrastructure or other risk assets; we are gong to park our money in bonds and wait for a catastrophe to unfold.

We are not there yet but yields backing up like this is offering interesting opportunities in the fixed income markets.

And don't forget, as long bond yields back up, pension liabilities go down a lot because the discount rate goes up. And if stocks hold up, that's great news.

Alright, let me wrap it up with the top-performing US large cap stocks this week (full list here):


And here are the worst-performing US large cap stocks this week (full list here):


And here is my biotech stock of the week, Viking Therapeutics (VKTX):


Do a deep dive here, only a matter of time before this company gets bought out at much higher multiples (read more here but most articles are terrible, look at the top holders and do your own due diligence). 

There are great biotech stocks out there, but I don't get paid enough to share all my secrets.

Below, the CNBC 'Halftime Report' Investment Committee breaks down its reaction to rising Treasurys and what it means for equities.

Also, yields are competing with stocks and the Fed just hiked, but Tom Lee says the market is missing two things: where inflation will be in six months, and which companies actually get stronger as rates rise.

Wages, inequality, and the roots of America’s affordability crisis

EPI -

This piece was originally published in American Educator, the professional journal of the American Federation of Teachers. Read it here. 

Outside of a crisis or recession, Americans’ perceptions of how the country and economy are being managed have never been so negative. Many have attributed this voter unhappiness to a crisis of “affordability.”

It is objectively true that it is too hard for most American families to afford a secure and dignified life. But the word “affordability” leads too many people—including policymakers—to fixate on prices. Affordability is not just about prices; instead, it’s the outcome of a race between incomes and prices.

This is not just economists quibbling. Focusing on prices will lead policymakers to ignore far too much of the useful playing field when thinking about what changes could make life better for working families.

In this article, we make the following arguments:

  • Far too many families are unable to afford a decent economic life.
  • The primary cause is a large increase in income and wage inequality, with incomes and wages for the vast majority of families lagging far behind what they could and should be.
  • This rise in inequality was caused by increasingly unequal “market” incomes (e.g., wages and salaries, returns on investments), while changes in taxes or transfers (e.g., Social Security, Medicare, unemployment insurance) slightly dampened the rise of income inequality.
  • The large rise in income inequality was driven by intentional policy changes that affected typical workers’ leverage and bargaining power in the labor market—and that means they can be reversed.
  • In capitalist economies (like ours), labor markets are inherently tilted toward employers—but historically and globally, broadly shared prosperity has only been achieved when policies that intentionally support workers (like strong unions, adequate minimum wages, and full employment mandates) have provided a countervailing force against employers’ power in labor markets. 
  • Much of the post-1979 period in the United States saw an assault on worker-friendly policies, and this led directly to the rise in inequality and to weak income growth for working families.

Americans’ economic dissatisfaction has real roots

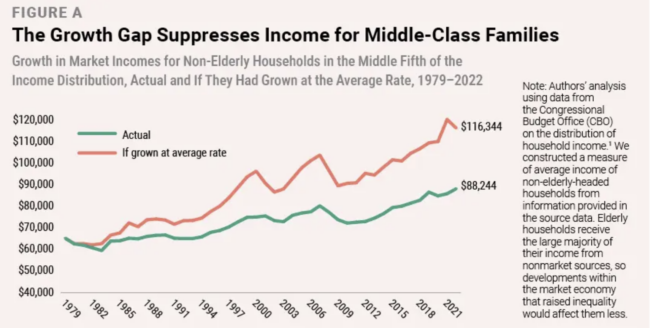
The U.S. economy is the richest in the world, yet the gap between what it could deliver to working families versus what it actually delivers is maddening. This gap can be measured with some precision. Figure A shows inflation-adjusted household income for the middle-fifth of U.S. families between 1979 and 2022, as well as what this growth could have been had it simply grown as fast as average incomes did in this period. 

This gap is driven by inequality. Average incomes can only rise faster than incomes at the middle if some groups—the ultra-rich in this case—see strongly above-average growth. This gap between average growth and growth experienced by the middle reached staggering levels by 2022 (the most recent data from the Congressional Budget Office). In that year, inequality’s rise since 1979 deprived middle-income families of an average of $28,100. Life for these families would be far more affordable today if they had this money coming in each year. And that’s well within our grasp. Average income growth is by definition attainable. All that’s needed are policies that ensure income growth is broadly shared, instead of policies that cause staggeringly fast income growth among the top 1% and much slower income growth for working people. 

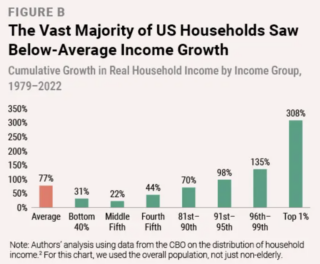
Figure B shows this inequality another way—charting average annual growth rates for the 1979–2022 period for a number of groups ranked by their position in the income distribution. The strikingly bad news from this figure is that only household groups above the 90th percentile saw income growth that matched or exceeded average income growth. How can more than 90% of households be below average when it comes to income growth? This is possible because the top 5%—and especially the top 1%—saw astoundingly fast growth over this period. 

For any given average growth rate, faster growth at the top of the scale must be matched by slower growth at the middle and/or bottom. It is this zero-sum dynamic of inequality, not anything to do with prices, that has been the crushing drag on regular Americans trying to afford a better life over time.

Staggering inequality is a choice

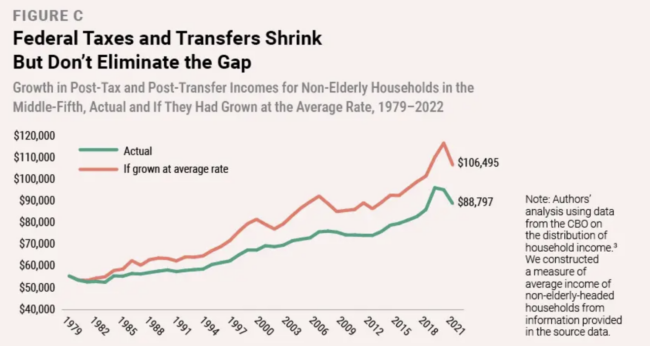
This growth in inequality has been driven by the rules governing markets—rules our elected leaders determine—not by taxes or transfers. Figure A showed the staggering $28,100 gap in market (pre-tax and transfer) income between what families in the middle-fifth actually made in 2022 versus what they could have made had inequality not risen. Figure C shows how large this gap is after the federal government gets involved on the tax and transfer side of the equation. 

Taxes obviously reduce incomes, but transfers (social insurance like Social Security and income support payments like unemployment insurance) raise incomes. For the middle-fifth of US households, this effect is largely a wash—their current income levels in Figures A and C are very similar. But because the United States still has a progressive federal tax system (though not as progressive as we would like), the rise of inequality in this post-tax and transfer data is slightly muted—i.e., federal taxes and transfers shrink the gap somewhat. By 2022, the annual gap after accounting for federal taxes and transfers is $17,698—still a sum of money that would be transformative for American families.

Essentially, federal taxes and transfers undid roughly one-third of the rise in income inequality, allowing rich households to pocket roughly two-thirds of their gains.*

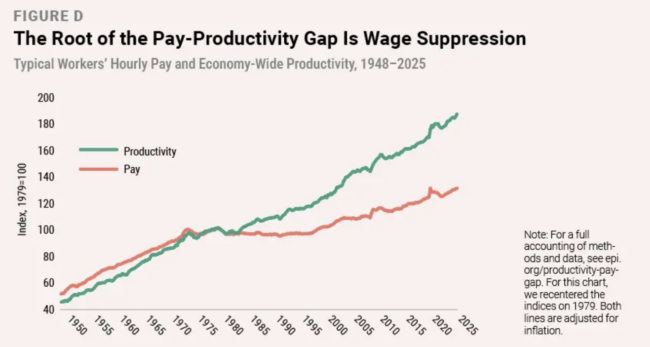
This rise in inequality was overwhelmingly driven by an intentional, multipronged policy campaign to suppress wages that was undertaken by shareholders, other capital owners, and corporate executives, with policymakers greasing the skids along the way.4 The primacy of wage suppression can be seen in Figure D, which compares the economy’s potential to pay higher wages and incomes with the actual hourly pay of typical workers in the United States. 

We measure the economy’s potential to pay higher wages by productivity, which is the output and income generated in the economy in an hour of work on average. And we define typical workers’ pay as the wages and benefits of workers in production and nonsupervisory positions, a group that constitutes over 80% of the economy’s private-sector workforce, excluding higher-wage managers and executives. As you see in the figure, in the three decades after World War II, productivity and pay mostly moved roughly in tandem, with typical workers’ pay rising 83% as fast as productivity. After 1979, these lines diverge sharply, with workers’ pay rising only about 43% as fast as productivity. 

If typical workers’ pay had risen in line with productivity growth in the years since 1979, their hourly pay would be 43% higher today. For a full-time, full-year worker making the median wage, this would constitute annual wages that are almost $23,000 higher.5 Where did that $23,000 go? Instead of paying workers more as their productivity rose, corporate executives, other already highly paid professionals, and shareholders captured those gains for themselves.

This growing gap between what shows up in typical workers’ paychecks and benefits versus the overall income being generated in the economy is the root story of American inequality and of today’s affordability crisis.

This pay-productivity gap can be decomposed into two parts: the portion driven by rising inequality in “labor” income (income earned from work), and the portion driven by a shift from labor income to “capital” income (income from investments, like when a stock increases in value). Growing inequality within labor incomes—earnings growing much faster among high-paying jobs than among middle- and low-paying jobs—accounts for almost 80% of the gap. The remaining 20% is accounted for by a shift from labor income to capital income.6 Below we say a bit more about each of these.

Rising inequality of labor incomes

The larger factor in the rise of overall income inequality is the growing inequality within labor incomes. This often surprises people, who assume the story of rising inequality is mostly one of the profits of rich corporations rising while most of their workers are left behind. It’s true that most workers in these corporations do not benefit, but the powerful employees who do prosper—CEOs and other executives—receive astronomical salaries that are classified as labor income in economic data, and these inflated executive salaries do cut into corporate profits. 

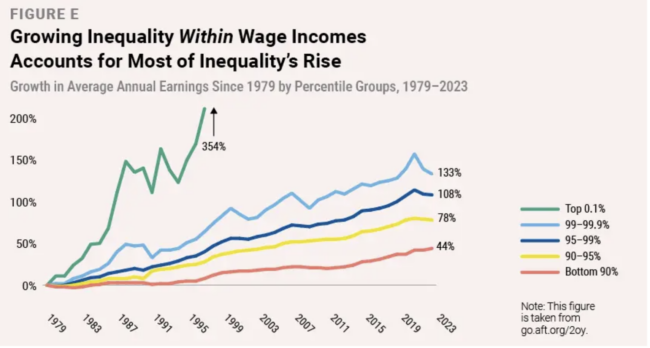
In addition, below the stratospheric level of corporate managers at large companies, there is a stratum of workers in medicine, legal services, and finance who command huge salaries. It’s not a large group of people, but the rise in their pay has been extreme. Figure E highlights this radical inequality within labor incomes, showing annual earnings of various wage groupings. (To keep the figure legible, pre-1979 data are not shown.) Prior to 1979, wage growth among very high wage workers—those in the top 10%, the top 1%, and the top 0.1%—was roughly in line with wage growth for the vast majority (i.e., for the bottom 90%). But between 1979 and 2023, cumulative growth in average annual earnings for the bottom 90% of workers was 44%, compared with 133% for the top 1%. For the top 0.1%, this growth was 354%—so high it doesn’t fit in the figure.

Given that labor income remains the large majority of all income generated in the economy, this huge rise in inequality within labor incomes is a key driver of the economy-wide march to greater inequality. Workers at the top of the wage scale were largely able to insulate themselves from the campaign of wage suppression launched by corporate owners. Of course, some of them were active participants in this campaign and got a significant cut of its benefits (think CEOs and lawyers for union-busting law firms). But the vast majority of workers (roughly 90%, as we see in Figure B) were on the losing side of this wage suppression campaign and found their wages falling far behind the economy’s potential to deliver strong and sustained wage growth. 

In some ways, the influence of rising inequality within labor incomes might be underestimated. For decades, U.S. tax policy has levied lower tax rates on capital income than labor income, and a great deal of capital gains escapes taxation entirely due to loopholes. 

Many of the same people who have been privileged enough to insulate themselves from wage suppression are also privileged enough to have excellent accountants who can make their incomes appear in whatever form results in the lowest taxes.7 For example, CEOs are overwhelmingly paid with “performance-based” measures, which means measures tied to the value of their companies’ stock prices. Twenty years ago, the large majority of this stock-based pay for CEOs came in the form of stock options, which are contracts that give the CEO the right (but not the obligation) to buy shares of stock at a set price. If the market price went above this set price, CEOs could exercise these options and pocket the difference as pay. The gains from exercised stock options are recognized by the IRS as labor income, taxed accordingly, and classified in data as labor income. But over the past two decades, there has been a pronounced shift in the stock-based pay of CEOs away from stock options and toward the outright granting of stock. In this case, CEOs are not given a right to buy shares at a preferential price; they are simply given shares.8 What’s important for the split between capital and labor incomes is that these non-option forms of stock-based compensation are far less likely to be captured in measures of wage incomes. So this tax evasion strategy artificially depresses estimates of labor income in the economy.

The shift from labor to capital incomes

While most of the pay-productivity gap stemmed from the rising inequality within labor earnings discussed above, a nontrivial portion of this gap stemmed from a shift in overall income from labor to capital. This goes far beyond the tax avoidance trick described above for CEO compensation—including paying regular working people less so that shareholders get more. If, for example, a corporation were able to suppress its workers’ pay while raising customers’ prices and/or cutting what it paid suppliers (which generally means those suppliers paying their workers less), it would earn higher profits. By successfully suppressing wages to boost profits, American corporations have made their stock more valuable. Imagine an investor buys $100 in company stock with the expectation of an annual return of $5. If the company undertakes a successful campaign of wage suppression that boosts annual returns to $10, many other investors will buy company stock—bidding up share prices.

So even though this labor-to-capital shift in overall income is the smaller player in generating overall income inequality, it still had profound effects on American economic life. Estimates indicate that anywhere from 40% to nearly 100% of the entire nominal gains in the U.S. stock market since 1989 can be attributed to this shift of income from workers to capital owners.9

The rise in US stock prices in recent decades is a key driver of another kind of economic inequality: inequality of wealth.† One of the primary sources of wealth, the ownership of corporate equities (e.g., shares of stocks), is incredibly concentrated; the top 10% of households own about 85% of all corporate equities, and the top 1% own nearly 40%.10

The concentration of corporate equities combined with the role of wage suppression in making these equities far more valuable leads to a clear implication: The wage suppression of recent decades is not just by far the biggest driver of the rise in income inequality; it is also by far the biggest driver of the rise in wealth inequality. Most of the rise in wealth inequality in recent decades has been the outcome of an intentional transfer away from workers to the top. 

Labor markets are not fair

This rise in inequality in recent decades has attracted much attention from researchers—along with everybody else struggling to pay for groceries and keep the lights on. For a long time, economists’ role in the debate over inequality was to look for reasons why well-functioning, competitive markets could generate lots of inequality. This often led to explanations that essentially blamed workers for the outcomes. The argument was that the fair and competitive labor market had spoken and that these workers were falling behind because their skills and efforts had been found wanting. The precise failure identified was often workers’ alleged inability to adapt to the quickening pace of technological change in the economy. 

But the evidence supporting this view of inequality driven by apolitical forces working through fair and competitive markets was incredibly thin.11 That led many researchers to examine whether labor markets are by their very nature tilted against workers, making it very difficult to secure regular raises that match overall economic growth. 

There is ample evidence for this view—that excess employer-side power makes labor markets generally unfair and inefficient, and that truly fair, competitive labor markets are the exception, not the rule. For example, many employers, and particularly those of low- and moderate-wage workers, rarely if ever negotiate pay; instead, they post take-it-or-leave-it wage offers.12 And when a given employer lets its wages lag behind those of potential competitors, workers’ exit from the lower-wage firm is far less common than would be predicted under truly competitive labor markets (where employers robustly compete for workers).13

This employer-side power is rooted in many obvious factors in real-world labor markets that make it hard for workers to effectively search for better jobs and, therefore, force employers to compete over them. These include things like lack of information about wages and benefits offered by other employers, transportation restrictions that require workers to look for jobs only in places near their homes or public transit nodes, and child care considerations that require a job’s location be compatible with picking up kids at a regular time, along with many other factors. 

Another barrier to competition is the obvious fact that in the short run, most employers need the income a new worker would generate for their business far less than most workers need the income from a job. In a jobsite of 100 workers, having a month go by understaffed by a single worker reduces business income by roughly 1%. In a household with a single worker, having a month go by without a job reduces income by essentially 100%. 

Employers exploit these barriers to employees finding better options by “marking down” wages below what would be necessary for employers to attract and retain workers in competitive labor markets. These markdowns can be large enough to push workers’ pay well below the value they produce for the employer (i.e., below the “market clearing” wage). This makes them not just unfair, but inefficient—a drag on economic growth. 

Key policy choices that led to rising inequality 

Having realized the role of employers’ power in determining labor market outcomes, the importance of specific policies is magnified. For example, before the 1990s, many economists were extremely skeptical that minimum wages could do much good in raising wages without steep downsides like job loss. Why? Because they erroneously used models of competitive labor markets. 

But more accurate models that include employers’ power reveal significant room to raise minimum wages without generating job losses. The evidence over the past 30 years has been highly persuasive that minimum wages could be much higher than they were in the 1980s and 1990s without causing job losses and that the benefits for low-wage workers would be large.14

The period of rising inequality since 1979 was one of profound institutional change in labor markets. The federal minimum wage, for example, lost 35% of its value between 1979 and 2025 as legislative inaction (i.e., not raising it) allowed it to be battered into irrelevance by inflation.15 This was also a period that saw a pronounced acceleration in the decline of unionization rates of American workers.16 It was a time when high levels of unemployment were tolerated by policymakers for extended periods in the name of fighting inflation.17 And it was a time when increasing integration between the rich United States and a poorer global economy was done on terms that were written by and for corporate interests.‡

Several years ago, researchers at our organization, the Economic Policy Institute, reviewed the research on how much specific policy choices likely contributed to growing inequality. Adding together the impacts of the changes like those listed above could easily explain the lion’s share of the rise in inequality since 1979.18

For example, one key policy change was the practical abandonment of the Federal Reserve’s full employment mandate. By law, the Fed is supposed to pursue both stable inflation and full employment (which means trying to keep unemployment as low as is consistent with stable inflation). But between 1979 and 2007 (right before the Great Recession), the Fed largely acted as if it did have a mandate to pursue stable inflation but did not have one to pursue full employment. 

After the Great Recession, the Fed admirably reversed course and tried to push the economy back to full employment, but its tools proved too weak given the magnitude of the shock. In such situations, fiscal policy—taxes and spending—should be used aggressively to restore full employment. But in the 2010s, political gridlock and excess caution kept policymakers from doing this, and much of that decade was plagued by excess unemployment. 

Excess unemployment does not just leave willing workers locked out of jobs. It also saps the ability of still-employed workers to demand raises. For nonunion workers, their chief leverage for getting wage increases is threatening to quit. This threat is only credible when unemployment is low. Consequently, the too-high unemployment rates for most of the period from 1979 to 2019 were a drag on wage growth. In our estimates, too-high unemployment may well have explained nearly a third of the entire pay-productivity gap over that period19—not to mention the devastation it wrought for millions of families.

Another key policy change was the failure to keep the playing field level between workers looking to organize and join unions and the employers who wanted to stop them. The National Labor Relations Board is supposed to safeguard this right, but its tools have proved too weak in the face of fierce employer opposition to unions, and policy changes to strengthen these tools have consistently been blocked. The results of throttling the growth of new unions have been profound; our estimates are that declining unionization likely explains a quarter of the pay-productivity gap since 1979.20 Crucially, the decline in unionization did not just hurt workers who otherwise would have been unionized. By far the biggest of the wage-suppressing effects of deunionization has been on the broad pool of nonunion workers. As unions lose strength, they stop being able to set industry-wide pay standards that even nonunion employers feel like they have to meet to avoid hemorrhaging employees. 

The wage-depressing effect of trade flows from poorer nations—flows encouraged by the corporate-led trade agreements the United States has signed in recent decades—can likely explain another 10 to 15% of the pay-productivity divergence since 1979.21

The wrong incentives

Tolerating excess unemployment, throttling workers’ ability to join unions, failing to update the minimum wage as costs rise, and signing corporate-friendly trade agreements were some of the many instruments of wage suppression undertaken and abetted by policymakers in recent decades. At the same time, choices legislators made on tax policy boosted the incentive for capital owners and corporate managers to aggressively use these instruments to increase their wealth. 

When ultra-high incomes and corporate profits are taxed at high (i.e., appropriate) rates, the incentives for powerful individuals to rig the rules of markets to suppress regular workers’ wages are much smaller. Key research shows that this incentive effect is real and powerful. For example, across countries, the larger the tax cuts on the rich enacted in recent decades, the greater the increase in pre-tax inequality.22 And, the lower the top tax rates for individuals, the higher the levels of pre-tax CEO pay.23 High taxes reduce the benefits of rule-rigging, so cutting taxes increases rule-rigging. This means that raising taxes on the richest households and corporations results in new revenue and more equal pre-tax incomes. But from the mid-1970s, tax rates for high-income households and corporations have been cut steadily and deeply in the United States, reducing both tax revenues and wages for working people.

Income inequality, not high prices, is behind the affordability crisis

We opened this article with a claim that affordability is the outcome of a race between income and prices. Our long walk through the economics and history of recent American inequality highlights that intentional policy choices have deprived typical households of income they could have otherwise claimed. Without this inequality, a middle-income household today would have tens of thousands of dollars more per year—and this would obviously make affording a decent life much easier. 

But some might wonder if we have still given prices short shrift in how much they contribute to affordability challenges. We don’t think so, for a number of reasons. We sketch three of them here.

First, all of the income, wage, and productivity statistics we have included in this article have been real (i.e., they have been adjusted for the impact of inflation). And it is unambiguously true that real (inflation-adjusted) incomes are the proper way to measure living standards and economic possibilities for households. 

Getting distracted by price growth while missing what’s happening with income will lead to wrong conclusions about economic performance over even relatively recent periods of time. Figure F compares two periods, both starting one year before a deep recession struck and then running five years: 2007–2012 and 2019–2024. In the first period, inflation averaged 1.8%, while in the second it ran more than twice as fast at 4.2%. Yet real (inflation-adjusted) wage growth for low- and middle-wage workers was far faster in the second period. For the lowest-wage workers, real wages fell by 2.1% in the first period but rose by 15.3% in the second. For workers in the middle of the wage scale, real wages fell by 1.5% in the first period but rose by 5.8% in the second. 

Over very short periods of time (one to two years), it is true that a rapid spike in prices tends to drive down real incomes and wages. But over any longer period (even as short as three to five years), assessing how the economy is doing for typical families rarely bears much relationship to price growth.

Second, even when researchers adjust for inflation differently at different parts of the wage and income distribution, the impact is modest. Such measures account for things like lower-income families spending a higher share of their income on rent and groceries and a lower share on vacations. But there are surprisingly small differences in overall price growth faced by families at different income levels. For example, from 2019 to 2025, when the price of housing and groceries was on peoples’ minds for good reasons, the inflation rate faced by the bottom 40% of households was just 0.2% higher than for the top 20% of households.24 In short, the growth in prices faced by different groups varies far less than the growth of their incomes and wages. 

Third, a key insight in assessing affordability debates is that one person’s cost is another person’s income. If the cost of a pound of coffee doubles from $10 to $20, this constitutes $10 of additional income that somebody is getting. Perhaps the coffee grower or the shipper or the grocery store shareholders or the CEO or the cashiers or some other link in the supply chain is getting an extra $10 (or several of them are getting some slice of it). This means that rapidly rising prices cannot result in less income overall, so they are highly unlikely to actually make an entire economy poorer. Instead, the groups that face only the price increase lose out while groups receiving the extra income win. 

This fact that every price is an amalgamation of various income streams also means policymakers can more usefully target wage and income policies rather than price policies. Again, my bill at the grocery store pays for the wages of cashiers, the pay of the company CEO, the dividends to shareholders, the payments to suppliers, and more. Even if we’re unhappy about this grocery bill, we likely don’t want all of those price components to get squeezed. We probably want the wages of cashiers to rise while hoping to rein in CEO pay and shareholder dividends. Policies that only look to restrain prices—price controls, for example—make no such distinction, so we don’t know who in the grocery supply chain will bear their burden (though we can guess it’s more likely to be the cashiers than the CEO). But if we raise minimum wages, change labor law to allow more widespread unionization, and raise taxes on the ultra-rich and on corporate profits, we have a very good idea of which incomes will be boosted and which will get squeezed.

Creating a fairer economy

It is deeply depressing that intentional policy acts led to the enormous rise in inequality that is making life so much harder for so many people. If tens of millions of American households had tens of thousands of extra dollars in their bank accounts each year while billionaires had significantly less money, the country would be a much better and happier place.

What brings us hope is the knowledge that because the rise in inequality was not the inevitable outcome of a modern economy, it can be halted and reversed. Today’s workers have the skills and abilities needed to support much higher incomes with no loss in efficiency or employment—if we change policy to give them these higher wages. This is excellent news. Of course, many of today’s elected leaders—and their donors—have little interest in reducing inequality, so the road ahead is long. But the foundational ingredients for a fairer and more efficient economy are clear: 

  • Keep unemployment rates low for long periods of time and fight recessions fiercely when they inevitably occur. 
  • Restore the right to organize new unions and bargain collectively. 
  • Raise minimum wages, including the federal minimum wage. 
  • Enact rules for the global economy that support healthy wage growth, not just healthy corporate profits. 
  • Crush the incentive to rig the rules of the economy by raising taxes significantly on ultra-rich households and corporations. 

The details on how we create a fairer economy are more complex—and they do matter! But understanding that the affordability crisis facing American families is overwhelmingly an inequality crisis is a necessary and useful place to start.

*Since this analysis goes through 2022, it does not include the tax or benefits cuts (including to Medicaid and the Supplemental Nutrition Assistance Program) in the One Big Beautiful Bill Act that President Trump signed into law in July 2025. These will further increase inequality.

†Wealth is the value of a person’s assets (e.g., the equity in their home, stocks and bonds in their retirement accounts, or their baseball card collections) minus the value of their debts.

‡For details, see “A Trade Policy That Puts Working Families First.” 

Footnotes

1. Congressional Budget Office, The Distribution of Household Income, 2022 (January 2026), cbo.gov/publication/61911.

2. Congressional Budget Office, The Distribution.

3. Congressional Budget Office, The Distribution.

4. For a much deeper dive into the specifics of this policy campaign of wage suppression, along with empirical assessments of how much it cost American families, see L. Mishel and J. Bivens, “Identifying the Policy Levers Generating Wage Suppression and Wage Inequality,” Economic Policy Institute, May 13, 2021, epi.org/unequalpower/publications/wage-suppression-inequality.

5. The median wage for U.S. workers in 2025 was $25.67. This (and a lot more) can be found at data.epi.org. Multiplying this median wage by 0.43 and then by 2,080 (hours worked by a full-time/full-year worker) yields the $23,000 figure.

6. Earlier estimates of how much inequality within wages contributed to the pay-productivity gap can be found here: L. Mishel, “Growing Inequalities, Reflecting Growing Employer Power, Have Generated a Productivity–Pay Gap Since 1979,” Working Economics Blog, September 2, 2021, epi.org/blog/growing-inequalities-reflecting-growing-employer-power-have-generated-a-productivity-pay-gap-since-1979-productivity-has-grown-3-5-times-as-much-as-pay-for-the-typical-worker. The easy way to update this (which we did for this report) is to compare productivity with growth in overall average compensation of American workers since 1979. This overall average compensation rose by roughly 76% since 1979. Given typical workers’ pay growth of just under 30%, this means that 46% (76% minus 30%) of the divergence between typical workers’ pay and productivity is a difference between typical workers’ pay and average pay.

7. See here for an estimate of how much of today’s reported capital incomes would be more properly classified as the returns to work (i.e., labor incomes): A. Eisfeldt, A. Falato, and M. Xiaolan, “Human Capitalists,” NBER Working Paper no. 28815, National Bureau of Economic Research, April 2022, nber.org/papers/w28815.

8. For more on CEO pay levels and their composition, see J. Bivens, E. Gould, and J. Kandra, “CEO Pay Has Skyrocketed Since 1978,” Economic Policy Institute, September 25, 2025, epi.org/publication/ceo-pay.

9. For this estimate, see D. Greenwald, M. Lettau, and S. Ludvigson, “How the Wealth Was Won: Factor Shares as Market Fundamentals,” Journal of Political Economy 133, no. 4 (April 2025): 1083–1132; and A. Atkeson, J. Heathcote, and F. Perri, A Macroeconomic Perspective on Stock Market Valuation Ratios (Federal Reserve Bank of Minneapolis, Research Division, January 2026), minneapolisfed.org/research/sr/sr682.pdf.

10. See Table 10 in: E. Wolff, “Household Wealth Trends in the United States, 1962 to 2019: Median Wealth Rebounds… but Not Enough,” NBER Working Paper no. 28383, National Bureau of Economic Research, January 2021, nber.org/system/files/working_papers/w28383/w28383.pdf.

11. For a much deeper dive into the weakness of claims that inequality was driven by technology rewarding skilled workers and penalizing less-skilled workers, see J. Schmitt, H. Shierholz, and L. Mishel, Don’t Blame the Robots: Assessing the Job Polarization Explanation of Growing Wage Inequality (Economic Policy Institute, November 19, 2013), epi.org/publication/technology-inequality-dont-blame-the-robots.

12. One study found that roughly 75% of low-wage jobs were ones where employers made take-it-or-leave-it posted offers: R. Hall and A. Krueger, “Evidence on the Incidence of Wage Posting, Wage Bargaining, and On-the-Job Search,” American Economic Journal: Macroeconomics 4, no. 4 (October 2012): 56–67; and R. Hall and A. Krueger, “Evidence on the Determinants of the Choice Between Wage Posting and Wage Bargaining,” NBER Working Paper no. 16033, National Bureau of Economic Research, May 2010, nber.org/system/files/working_papers/w16033/w16033.pdf.

13. For evidence on how nonresponsive worker quits are to wage cuts relative to predictions of competitive markets, see A. Dube, L. Giuliano, and J. Leonard, “Fairness and Frictions: The Impact of Unequal Raises on Quit Behavior,” American Economic Review 109, no. 2 (February 2019): 620–63.

14. For a comprehensive review of this evidence, see D. Cengiz et al., “The Effect of Minimum Wages on Low-Wage Jobs,” Quarterly Journal of Economics 134, no. 3 (August 2019): 1405–54.

15. Economic Policy Institute, “Minimum Wages: Real Minimum Wage (2025$),” 2026, data.epi.org/minimum_wage/minimum_wage_levels/line/year/national/real_minimum_wage_2025/overall?timeStart=1938-01-01&timeEnd=2025-01-01&dateString=1979-01-01&highlightedLines=overall.

16. P. Romero and J. Whittaker, A Brief Examination of Union Membership Data (Library of Congress, June 16, 2023), congress.gov/crs-product/R47596; and H. Meyerson, “Economic Inequality Is Undermining America: Worker Solidarity Will Build a Better Future,” AFT Health Care 3, no. 2 (Fall 2022): 33–36.

17. S. Galan, “Monthly Federal Funds Effective Rate, Unemployment Rate and Inflation Rate in the U.S. During Paul Volcker’s Terms as Federal Reserve Chairperson from 1979 to 1987,” Statista, October 2022, statista.com/statistics/1338105/volcker-shock-interest-rates-unemployment-inflation/?srsltid=AfmBOoqoXQ4yTpqiSJMevwNFbnNGEETrwhlltEeVrJuA1rThyYCBBkFl.

18. Mishel and Bivens, “Identifying the Policy Levers.”

19. J. Bivens, “Focus on the Boom, Not the Slump—the Fed’s New Policy Framework Needs to Stop Cutting Recoveries Short,” Working Economics Blog, Economic Policy Institute, June 18, 2019, epi.org/blog/focus-on-the-boom-not-the-slump-the-feds-new-policy-framework-needs-to-stop-cutting-recoveries-short-epi-macroeconomics-newsletter.

20. Mishel and Bivens, “Identifying the Policy Levers.”

21. Mishel and Bivens, “Identifying the Policy Levers.”

22. A. Fieldhouse, Rising Income Inequality and the Role of Shifting Market-Income Distribution, Tax Burdens, and Tax Rates (Economic Policy Institute, June 14, 2013), epi.org/publication/rising-income-inequality-role-shifting-market.

23. J. Bivens, “Using Tax Policy to Restrain CEO Pay: Best Practices and Smart Alternatives,” Economic Policy Institute, December 13, 2023, epi.org/publication/using-tax-policy-to-restrain-ceo-pay-best-practices-and-smart-alternatives.

24. Authors’ analysis of data obtained from: Federal Reserve Bank of New York, “Economic Heterogeneity Indicators (EHIs),” 2026, newyorkfed.org/research/economic-heterogeneity-indicators.

OMERS Promotes Laura Lenz to Lead Ventures Amid Canada-First Push

Pension Pulse -

Sean Silcoff of The Globe and Mail reports OMERS promotes Laura Lenz to lead venture capital unit:

Ontario Municipal Employees Retirement System has appointed Laura Lenz to head its venture capital arm, the fourth person to hold the job in just over three years, while signalling a continued commitment to backing Canadian technology founders.

Ms. Lenz, a veteran early-stage capital investor who joined OMERS Ventures in 2019 and oversaw its Canadian investments, replaces Saar Pikar, who left in July after just one year on the job to lead Kensington Capital Partners Ltd. He in turn had replaced Michael Yang, who departed two years after replacing Damien Steel, who left in 2023 to lead climate technology startup Deep Sky Corp.

“We have a fantastic track record in Canada, and I’m excited to continue building,” said Ms. Lenz, who started her career as an associate with BMO Capital Markets before taking on investor roles at EdgeStone Capital Partners, MaRS Investment Accelerator Fund and Geoff Beattie-led Generation Ventures. “I know the people, I know our portfolio, I know our strategy.”

OMERS private capital head Michael Block said in an interview: “We have tremendous confidence in her and her whole team. She is very thoughtful and conscious about risk. She’s built a great network of relationships with founders in Canada and has a great reputation.”

OMERS Ventures started in 2011 when then-CEO Michael Nobrega brought on John Ruffolo to back promising Canadian tech entrepreneurs. The timing was ideal. While the Canadian venture capital industry was reeling following the retreat of institutional investors during the 2008-09 credit crisis, the tech startup world was rife with opportunity, as smartphones, cloud computing and artificial intelligence proliferated.

OMERS Ventures made early bets on future Canadian champions including Shopify Inc., Xanadu Quantum Technologies Ltd. and Hopper Inc. It expanded to Britain and the United States and began managing third-party capital before Mr. Ruffolo departed in 2018.

But OMERS Ventures’ relative prominence in the ecosystem faded as other domestic tech financiers including Georgian, Inovia Capital and Radical Ventures amassed billions of dollars in assets.

The information technology sector entered a prolonged slump in 2021 – with the exception of artificial intelligence and quantum computing – and the rise of AI-powered companies weighed on valuations of cloud-software companies, including many held by OMERS Ventures. OMERS this year sustained a nine-figure loss after TouchBistro Inc., which OMERS Ventures and OMERS Growth had backed heavily in the 2010s, was bought by Constellation Software for $100-million.

By then OMERS Ventures had stopped investing in Europe to focus primarily on Canada and shed much of its staff. Today it has four partners including Ms. Lenz, five associates and a principal.

The changes stem from a broader review of OMERS’s private-equity business, which has pivoting toward more investing through third-party funds and as a co-investment partner, with a North American focus. OMERS has also stopped making new growth-stage investments in more mature tech companies through a separate group.

At the same time, Ontario Teachers’ Pension Plan has amassed more than $25.9-billion in investments by financing some of the hottest technology names in the world through its venture growth arm TVG, including Anthropic PBC, Space Explorations Technology Corp. (SpaceX), Databricks Inc. and legal AI software vendor Harvey AI Corp.

OMERS Ventures, which has about $2-billion allocated to venture investments – roughly 1 per cent of the pension giant’s assets – has made four investments in each of the past three years. It has continued to back high-profile emerging Canadian tech names, including Cohere Inc., Waabi Innovations Inc., Float Financial Solutions Inc. and Dominion Dynamics. Its stake in Xanadu, despite a recent selloff, is still worth more than US$200-million –a sizable gain given it invested less than US$30-million for its stake.

Ms. Lenz said OMERS Ventures’ refocusing on Canada has worked out. “It’s where our network is. It’s where our best performing companies are. We have a lot of opportunity here,” she said. She said OMERS is looking to invest $5-million to $15-million per company, focusing on rapidly expanding AI-first businesses led by “ambitious founders that have a global market opportunity.”

Mr. Block said OMERS Ventures would continue “the same direction of travel” under Ms. Lenz and that the pension fund doesn’t plan to increase its allotment to venture capital. But, he added, “we’re open minded. We look at opportunities as they come. We just see a really good opportunity to focus on what we’re focused on.” 

Lauren Bailey of Markets Group also reports OMERS taps Laura Lenz to lead Ventures amid Canada-first push:

The Ontario Municipal Employees Retirement System (OMERS) has appointed Laura Lenz managing director and head of its Ventures platform as the fund doubles down on backing Canadian technology companies and founders.

Her appointment comes as OMERS more broadly increases its exposure to Canada. The pension fund, which had C$151.6 billion in net assets as of June 30, has committed to making at least C$10 billion in new Canadian investments over five years and deployed an additional C$1 billion into Canadian equities during the first half of 2026.

“[Lenz] brings the experience, judgment and deep understanding of founders needed to lead OMERS Ventures into its next chapter,” said Michael Block, head of private capital, in a press release. “She will build on the strength of an experienced team with a continued focus on supporting high-potential companies, deploying capital with conviction and helping founders build businesses that can scale globally.”

Lenz has been with OMERS Ventures for seven years and has worked in venture capital since 2004. She brings experience across venture capital, growth investing and company building, along with a strong understanding of founders, technology companies and the Canadian innovation ecosystem.

The appointment builds on leadership changes OMERS implemented within its Ventures group last year, when Lenz was promoted from partner to managing director as the platform increased its focus on Canada while continuing to pursue selective opportunities in the U.S.

Founded in 2011 with its first investment in Toronto-based Wave, OMERS Ventures has backed 46 Canadian companies, including Shopify, Xanadu, D2L, Float, Hopper, Jobber, League, OneVest, Solink, Wave Accounting, Wattpad and Waabi. More recently, it backed Cohere and Dominion Dynamics, participating this year in Dominion Dynamics’ C$139 million Series A funding round.

Under Lenz’s leadership, OMERS said the platform’s focus will continue to be Canada first, backing ambitious founders and category-defining companies while using OMERS’ global network, scale and flexible capital to help founders access capital, customers and growth opportunities.

In a LinkedIn post announcing her appointment, Lenz said OMERS Ventures has two additional investments that have yet to be publicly announced. She grouped those investments alongside Cohere and Dominion Dynamics as examples of where the platform sees the next generation of important companies emerging: at the intersection of artificial intelligence, infrastructure and software.

Lenz also outlined the platform’s investment strategy going forward, noting OMERS Ventures plans to target exceptional early-stage companies with initial investments of C$5 million to C$15 million and remain a meaningful partner as those businesses scale.

“We are a venture platform with the ability to invest early, support companies through scale and bring more than capital to the table,” Lenz wrote.

Today, OMERS Ventures announced the appointment of Laura Lenz as Managing Director, Head of Ventures, backing the next generation of global companies:

OMERS Ventures today announced that Laura Lenz has been appointed Managing Director, Head of Ventures, marking the next chapter for the platform as it continues to back ambitious founders building globally competitive companies from Canada and beyond.

“Laura brings the experience, judgment and deep understanding of founders needed to lead OMERS Ventures into its next chapter,” said Michael Block, Head of Private Capital. “She will build on the strength of an experienced team with a continued focus on supporting high-potential companies, deploying capital with conviction and helping founders build businesses that can scale globally.”

Lenz has been with OMERS Ventures for seven years and has worked in venture capital since 2004. She brings deep experience across venture capital, growth investing and company building, along with a strong understanding of founders, technology companies and the Canadian innovation ecosystem.

“Venture is ultimately a people business,” said Lenz. “The best outcomes come from trust, judgment, conviction and partnership. My priority is to build on that foundation: creating an environment where different perspectives are valued, individual conviction is encouraged and our collective standard remains high.”

Founded in 2011 with its first investment in Toronto-based Wave, OMERS Ventures has been an early and long-standing supporter of Canadian companies, founders and the broader venture ecosystem. Since inception, OMERS Ventures has backed 46 Canadian companies, including Shopify, Xanadu, D2L, Float, Hopper, Jobber, League, OneVest, Solink, Wave Accounting, Wattpad, Waabi, with more recent investments in Cohere and Dominion Dynamics.

Under Lenz’s leadership, OMERS Ventures’ focus will continue to be Canada first: backing ambitious founders and category-defining companies, while using OMERS global network, scale and flexible capital to help founders access capital, customers and growth opportunities.

“The ambition has been here in Canada,” said Lenz. “What is changing is our willingness to build around it. At OMERS Ventures, our part is clear: back exceptional founders early, bring meaningful capital and conviction, use the full strength of the OMERS network where it can help, and support those founders in building companies that can compete with anyone, anywhere.”

As part of OMERS, one of Canada’s largest pension plans, OMERS Ventures is able to connect founders with institutional expertise, global relationships and sector knowledge across markets and geographies. That platform advantage supports the team’s goal of helping companies scale while creating long-term value for OMERS members, and aligns with OMERS broader commitment to invest $10 billion more in Canada over approximately the next five years across asset classes.

OMERS Ventures sees a strong opportunity set in Canada, particularly in areas where AI is creating or reshaping markets, including defence technologies, physical AI, and vertical AI platforms built for specific industry workflows. Next week, OMERS Ventures will host its annual AI Assembly Summit, bringing together leading Canadian and international investors, founders and industry experts to discuss how artificial intelligence is reshaping venture capital, infrastructure, defence, robotics and the broader investment landscape.

Alright, big announcement at OMERS Ventures which has seen a lot of turnover at the helm recently after Saar Pikar, the former head, left the pension fund in July to become president of Kensington Capital Partners Ltd.

That move marked the third time in three years that the OMERS Ventures unit has changed hands. Damien Steel left in 2023. Michael Yang, its most senior venture capital leader, followed two years later. 

Hopefully, Ms. Lenz will stick around longer than her predecessors. She has the experience and judgment and an interesting background with great and authentic perspective:

Growing up, the dinner table was my first conference room. My dad's investment banking background merged with my mom's nursing career, and our family’s passion for art, created the foundation for a rich tapestry of conversation. From an early age I was captivated by financial narratives.

‍I also loved languages. I started teaching myself Spanish in 4th grade and Japanese in 7th grade. My love of languages would lead me to spending time studying or working in Mexico,Tokyo and Peru at various points in my life, ensuring that today I look at most things through a truly global lens. My fascination with Japan was directly linked to my martial arts practice. I still train regularly today and currently hold black belts in Karate and Tae Kwon Do. Not only did martial arts instill in me a deep sense of respect for the role of health in my ability to succeed, but it taught me a level of discipline I still draw upon today.

‍After a finance-focused undergrad and working in Tokyo and New York City, I discovered my love for private markets - and venture capital in particular - at Edgestone in 2004. It was one of Canada's few early-stage tech funds at the time. And at $104M it was one of the biggest! Working alongside two operators, I honed my investing skills, learning that respect and humility are just as vital as vision and strategy.

While in banking, I was involved in a significant IPO at the time – 724 Solutions – it was a payments engine and soared to a market cap larger than the Bank of Montreal (where I worked at the time). It was quite a journey and helped me to understand a bubble early in my career. 

‍Today, I am most interested in looking at companies operating at the intersection of fintech and commerce - I call it financial value exchange. The areas of fintech I get most excited about include data exchange and enrichment; companies providing the orchestration layer to manage and drive insights from the multitude of applications and point solutions that exist in an enterprise; fraud and identity management; and agile billing platforms that enable companies to be flexible and responsive in their pricing models. I’m also passionate about the ability for technology to unlock financial literacy, and products for those who have traditionally been underserved. I like products that are emerging to prevent people with low incomes from getting trapped in endless debt cycles.

‍What should founders know about me?

When I sit on your board, my role is to engage in candid, constructive dialogue that propels your company forward. I bring a holistic perspective to the challenges and opportunities facing your business. Whether it's connecting you with the right talent or customers, I'm all in. But I will never shy away from telling you what I really think. It is this transparency that has helped me create long lasting relationships with founders I’ve backed over the last two decades.

And yes, I may be intense but I am far from robotic. The humanity in business matters to me a lot. Whether it's dealing with employees or investors, people are not just line items on an income statement; they're the essence of any successful endeavour.

‍Despite the fact that my finance career began in the late nineties it was a different era. I was regularly the only woman in the room. And was referred to as ‘sweetheart’ more often than I care to admit. As a result of this - and the fact that I am raising a child with a physical disability - it has been important to me throughout my career to ensure that wherever I work we are creating space for diverse voices to get heard. 

‍While I'm a strong advocate for Canadian talent, my love for languages and diverse cultures runs deep in my DNA. This blend of local pride and international vision defines me, both as a person and an investor. 

Very impressive. I think OMERS Ventures has found itself an exceptional leader, and I do wish her a lot of success.

I've seen it all in venture cap: the good, the bad and downright ugly (I was at BDC in 2008, VC got massacred).

It's not an easy game but necessary and can be lucrative (just look at OTPP's success with SpaceX, and soon Anthropic and other companies in its portfolio, including Harvey, the leading AI legal platform). 

For it's part, OMERS Ventures has done very well with Xanadu despite that stock's recent selloff. 

Its Canadian focus comes at the right time but there is competition in the space.

I recently covered the Canada Investment Summit where I noted Radical Ventures launched Canada’s largest AI fund with $1-billion USD first close and lots of top Canadian pension funds backing it.

I said Canada's VC industry desperately needs major capital and expertise to nurture startups into mature growth companies. Hopefully this new fund will be a huge success.  

I wish the same for OMERS Ventures as Laura Lenz takes over the helm.

Just remember, venture cap is never an easy game; you can allocate $5 million or more to 100 companies and are lucky if one or two hit a home run (or grand slam like SpaceX). 

This is why pension funds typically allocate between 1 and 3% of their total assets to venture cap/ growth equity. 

Alright, let me wrap it up there.

Below, from two years ago, the kickoff CIX Summit with Co-chairs Laura Lenz, (then) Partner at OMERS Ventures and Alison Nankivell, Senior Vice President, Fund Investments at BDC Capital, discussing the current state of the Canadian market, venture capital investing, and the future of the Canadian tech landscape. Great insights from both of them.  

Pages